| | | | | | | | | BRAINVEST WEEKLY MARKET HIGHLIGHTS WEEK 44 2ND TO 8TH NOVEMBER 2026 |
| | • Markets - the AI trade faced a political reality check:
What initially appeared to be another resilient week for financial markets turned into a sharp reversal, as the Democratic sweep in the US midterm elections increasingly weighed on investor sentiment, culminating in a particularly severe sell-off on Thursday. US equities led the decline, with the Nasdaq (-3.4%) and S&P 500 (-2.7%) retreating amid renewed pressure on the AI trade. International markets proved more resilient, with Europe (+0.3%) holding up and India (+8.7%) standing out, while Japan (-6.5%) and Emerging Markets (-4.1%) suffered significant losses. Sovereign bonds benefited from the risk-off environment, with US 10-year yields declining 7bps to 4.86%. Meanwhile, oil plunged 12.8% to $91, Gold rallied 5.1%, and Bitcoin declined 2.5%. |
| | • US midterms - a blue wave threatens the AI investment boom:
The Democratic Party delivered a sweeping victory in the midterm elections, regaining control of both chambers of Congress and securing important state-level victories, including Texas, a strategic hub for US data-center development. While markets initially welcomed the results, attention quickly shifted to the potential consequences for the AI investment cycle. Opposition to data centers emerged as a significant electoral issue, with voters backing numerous local restrictions amid concerns over electricity costs, water consumption and tax incentives. The prospect of tighter regulation and slower project approvals has introduced a new political risk for an industry already facing questions over the scale and financing of its capital expenditure. |
| | • US economic activity - the labor market shows renewed strength:
October's employment report delivered a substantial upside surprise, with 165K jobs created against expectations of just 65K, while the unemployment rate declined to 4.1% from 4.2%. Previous months were also revised higher by a combined 84K jobs, reinforcing the picture of a labor market that remains remarkably resilient. September job openings increased to approximately 7.5 million, providing further evidence of sustained labor demand. Broader economic activity also remained robust, with October's ISM Manufacturing PMI rising to 55.5, its tenth consecutive month of expansion, while Services remained firmly in expansionary territory at 54.5. |
| | • Emerging Markets - Brazil pauses easing as Mexico surprises:
Brazil's central bank unanimously held the Selic rate at 13.75%, ending five consecutive rate cuts following President Lula's re-election. The decision reflected a deterioration in the inflation outlook, with renewed fiscal concerns contributing to rising inflation expectations. Importantly, policymakers removed previous language pointing toward further easing, suggesting a more cautious stance ahead. Meanwhile, Mexico's central bank surprised markets by cutting its policy rate by 25bps to 6.25%, in a closely contested 3–2 decision. The contrasting outcomes highlight increasingly divergent monetary policy paths across Latin America's two largest economies. |
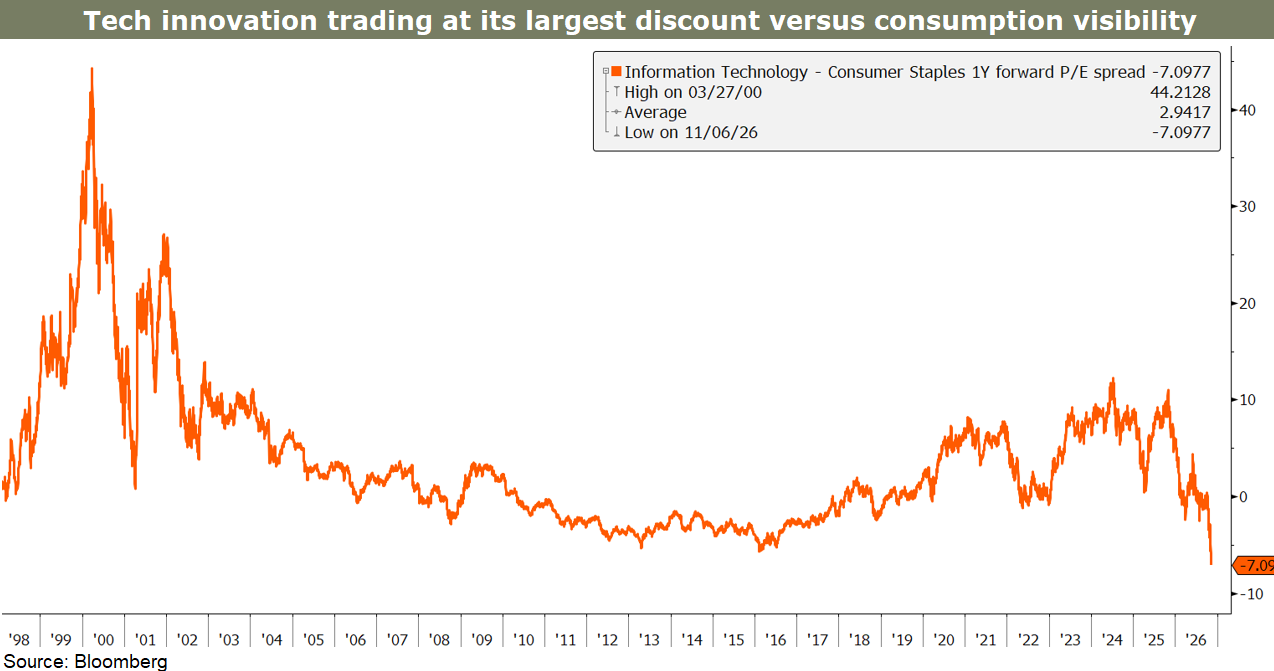
| | • Chart of the week - investors are paying a premium for predictability over innovation
An interesting shift is emerging in how investors value different parts of the US equity market. Despite the extraordinary pace of technological innovation, growing uncertainty surrounding AI-related capital expenditure, financing needs and future returns has made investors increasingly reluctant to pay a valuation premium for technology stocks. Instead, that premium is now reflected in traditionally defensive sectors such as Consumer Staples, where earnings visibility, recurring demand and cash-flow predictability offer greater comfort. Particularly in an otherwise resilient economic environment, this striking divergence suggests that investors are increasingly willing to pay more for certainty than for growth potential alone. |
| | • What investors will be looking at this week:
US inflation will take center stage, with October’s CPI report providing a crucial test of persistent price pressures and potentially reshaping expectations for a December Fed hike. Several Fed officials are also scheduled to speak, offering further clues on the monetary policy outlook. Beyond macroeconomic developments, investors will closely monitor sentiment surrounding the AI trade, as concerns over massive capital expenditure, financing requirements and future profitability continue to weigh on the sector. Following last week’s sharp sell-off, markets will be looking for signs of stabilization. |
| | | | | | | | | | | | |