| | | | | | | | | BRAINVEST WEEKLY MARKET HIGHLIGHTS WEEK 41 12TH TO 18TH OCTOBER 2026 |
| | • Markets - technology stocks come under pressure:
A sharp sell-off in semiconductors dominated a difficult week for global markets, with the Philadelphia Semiconductor Index (SOX) plunging 12% amid mounting concerns over AI valuations and the sustainability of massive infrastructure spending. Fears surrounding the financing of the AI investment boom also intensified, reflected in a sharp widening of credit default swap (CDS) spreads for several major companies exposed to the sector. The Nasdaq (-4.5%) and S&P 500 (-1.9%) retreated, while European equities proved more resilient, led by Switzerland (+4.4%). Emerging Markets (-5.9%) suffered a particularly difficult week, with China (-3.4%) among the main laggards. Meanwhile, US 10-year Treasury yields declined 16bps to 5.08%, supporting fixed income returns. Oil surged 10.7% to $102 amid persistent geopolitical tensions, while Gold slipped 0.6% and Bitcoin declined 2.4%. |
| | • US inflation - a hotter print, but an October hike remains unlikely:
September's CPI report came in hotter than expected, with headline inflation accelerating to 3.7% YoY from 3.4%, largely driven by higher energy prices. Monthly inflation reached 0.6%, while Core CPI increased 0.3% MoM and 2.6% YoY, reinforcing concerns that underlying price pressures remain persistent. While the upside surprise complicates the Fed's policy outlook, markets continue to overwhelmingly expect a pause at the October meeting, particularly following recent dovish comments from Fed officials. Nevertheless, another rate hike in December cannot be entirely ruled out should inflation remain elevated. |
| | • US earnings - banks kick off another promising reporting season:
The Q3 earnings season began with a mixed but broadly encouraging set of results from major US banks. Goldman Sachs stood out, reporting a 29% increase in profits, supported by particularly strong equities trading revenues (+72%) and resilient investment banking activity. Citigroup also delivered solid results, while JPMorgan and Wells Fargo presented a more nuanced picture. Looking beyond the banking sector, expectations remain exceptionally high, with S&P 500 earnings forecast to grow approximately 25 - 30% YoY, potentially marking a third consecutive quarter of earnings growth exceeding 25%, largely supported by AI-related investment and technology companies. |
| | • IMF / World bank - resilience comes with growing vulnerabilities:
The IMF and World Bank Annual Meetings highlighted an increasingly complex global economic outlook. The IMF marginally raised its 2026 global growth forecast to 3.1%, supported by strong AI-related investment, but warned that the recovery remains vulnerable to geopolitical tensions and persistent energy shocks. Three concerns dominated discussions: the sustainability of AI-driven growth, mounting public debt burdens and the uneven impact of inflation across economies. With global growth remaining below historical averages, policymakers emphasized the need to rebuild fiscal buffers while ensuring that technological investment translates into broader productivity gains. |
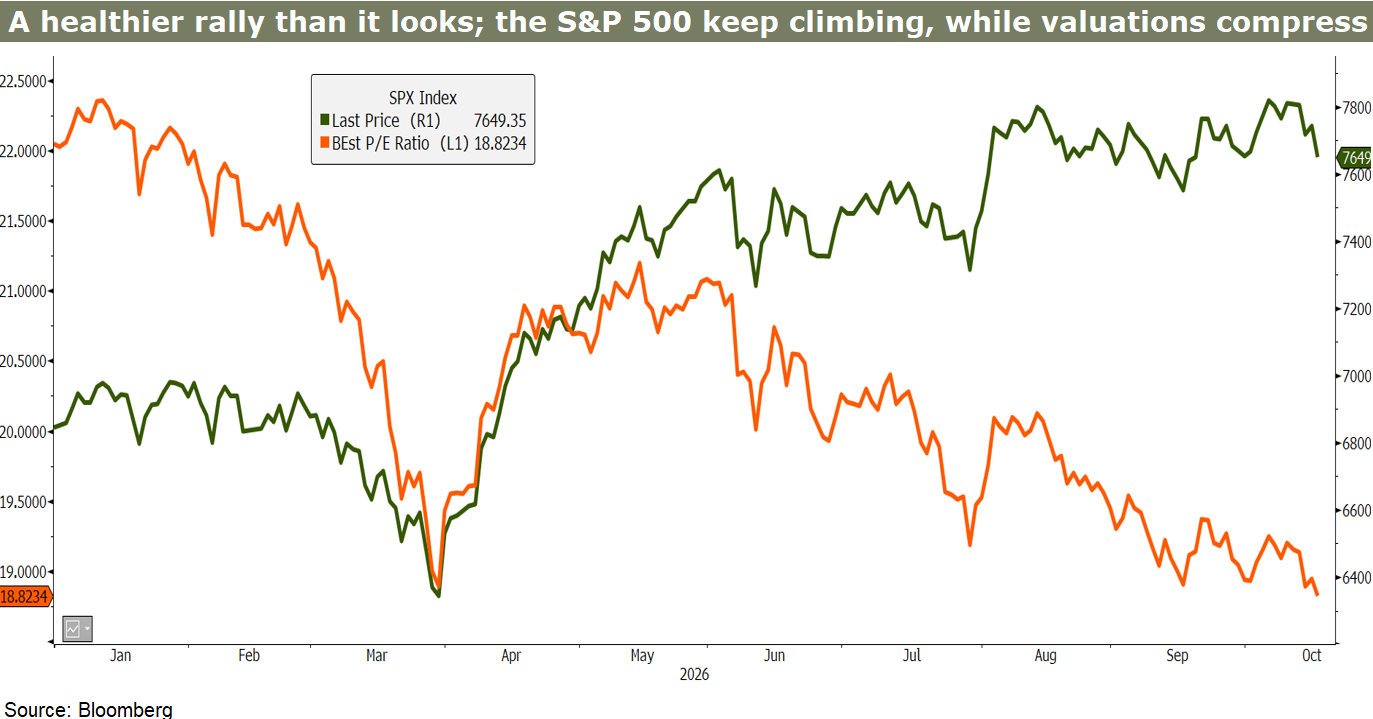
| | • Chart of the week - a healthier equity rally than it looks ?
Despite persistent concerns over stretched US equity valuations, an interesting divergence has emerged beneath the surface. The S&P 500 remains up more than 14% YTD, even as its forward P/E ratio has compressed from roughly 22x at the beginning of the year to below 19x today. In other words, strong earnings growth and upward revisions to profit expectations have more than offset the decline in valuation multiples. While this does not eliminate concerns around market concentration or elevated absolute valuations, it suggests that the rally has increasingly been supported by improving fundamentals rather than multiple expansion. |
| | • What investors will be looking at this week:
This week will be all about earnings, earnings, earnings. After the major U.S. banks kicked off the Q3 reporting season, results will now broaden across sectors and continents, with technology taking center stage as Meta, Netflix, Tesla and other major names report. On the macro side, China will open the week with Q3 GDP, retail sales and industrial production, before attention shifts back to the U.S., where housing data and consumer sentiment will round out the week on Friday. |
| | | | | | | | | | | | |